In the fast-moving commercial environment of the UAE, bookkeeping errors, omitted supplier tax invoices, incorrect zero-rating applications, and miscalculated corporate tax provisions happen even in well-run businesses. However, what separates an easily resolved minor discrepancy from an existential financial crisis involving tens of thousands of Dirhams in FTA administrative penalties is single-handedly determined by one factor: Who discovers the mistake first—you, or the Federal Tax Authority?
1. What is an FTA Voluntary Disclosure?
A Voluntary Disclosure is a formal declaration submitted digitally by a taxable person through the EmaraTax portal to notify the Federal Tax Authority of an error, omission, or under/over-calculation in a previously filed Tax Return (Form VAT201 or Form CT201), Tax Assessment, or Tax Refund Application (Form VAT311).
Filing a Voluntary Disclosure is not an admission of wrongdoing; rather, it is the legally established statutory mechanism for self-correction under UAE law. When executed professionally by a licensed FTA-approved Tax Agent, it demonstrates proactive compliance and safeguards company directors against allegations of deliberate tax evasion.
2. When is a Voluntary Disclosure Legally Mandatory? The AED 10,000 Rule
Under Article 8 of the Tax Procedures Law, taxpayers are not required—nor allowed—to submit a Voluntary Disclosure for every trivial clerical oversight. The legislation establishes a clear financial threshold:
🚨 Scenario A: Understated Tax EXCEEDS AED 10,000
If an error in a previous VAT or Corporate Tax return caused your payable tax to be understated (or recoverable refund overstated) by more than AED 10,000, submitting a formal Voluntary Disclosure via Form 211 is MANDATORY within 20 business days of discovering the mistake.
ℹ️ Scenario B: Error is AED 10,000 or LESS
If the net tax difference does not exceed AED 10,000, you are not required to submit Form 211. Instead, you can simply adjust the error in Box 14 (Tax Adjustments) of your next routine quarterly VAT Return (Form VAT201) without incurring any disclosure filing fees.
3. The Strict 20 Business Day Statutory Window
Timing is paramount. Under UAE Tax Procedures Executive Regulations, once a taxable person identifies an error exceeding AED 10,000—whether through an internal management accounts reconciliation, year-end statutory audit, or supplier invoice review—they have precisely 20 business days to submit the Voluntary Disclosure on EmaraTax.
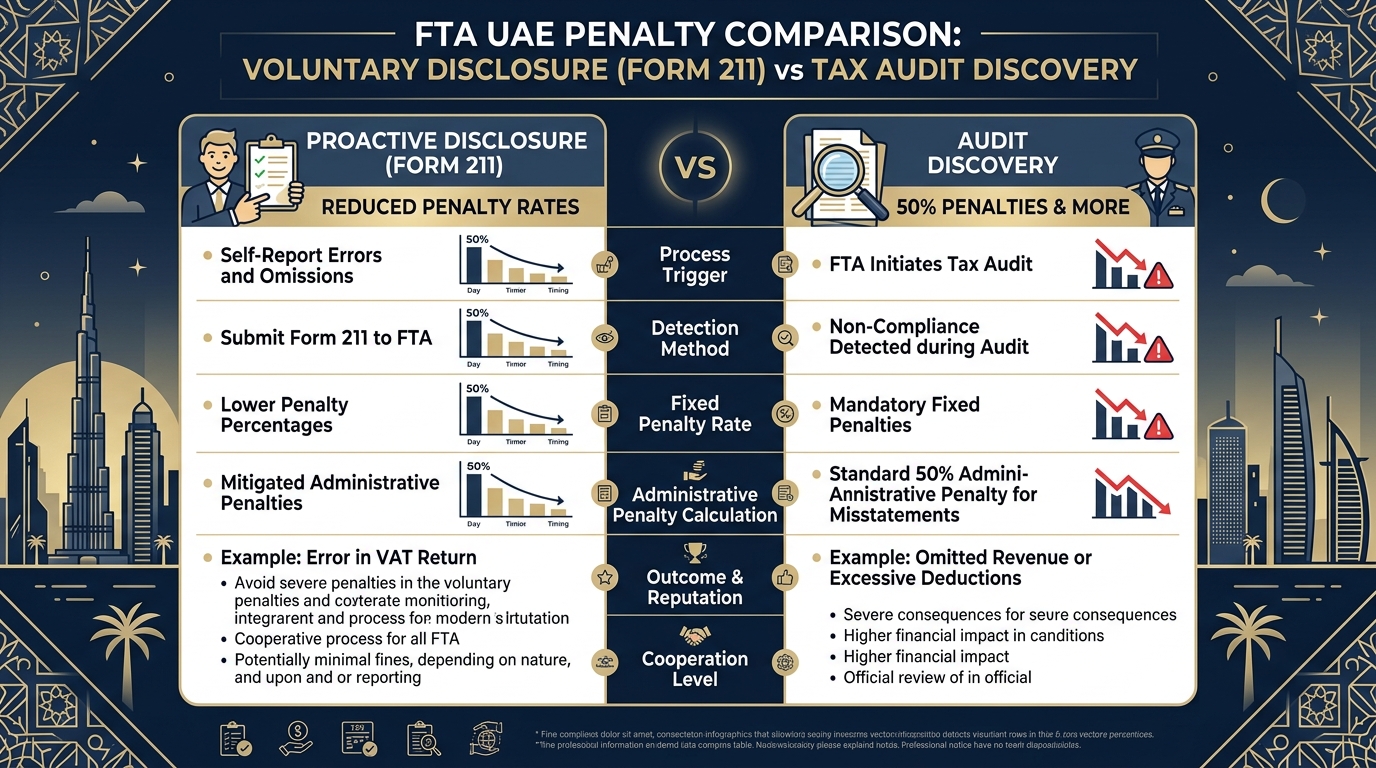
4. Penalty Comparison: Proactive Submission vs. FTA Tax Audit Discovery
Cabinet Decision No. 40 of 2021 and Cabinet Decision No. 75 of 2023 establish tiered administrative penalties based on the degree of taxpayer cooperation and notification status:
| Compliance Scenario | Fixed Administrative Fine | Percentage Penalty on Tax Variance |
|---|---|---|
| 1. Proactive Voluntary Disclosure (No Audit Notification) | AED 1,000 (first time) / AED 2,000 | 5% to 10% (depending on settlement window) |
| 2. Voluntary Disclosure AFTER FTA Audit Notification (Form 301) | AED 1,000 / AED 2,000 | 30% flat penalty |
| 3. Error Discovered Directly by FTA Tax Inspector during Audit | AED 5,000 + Assessment Notice Fines | 50% punitive tax assessment penalty |
As demonstrated above, filing a voluntary disclosure proactively saves your company up to 40% to 45% in direct penalties, plus avoids costly legal disputes before the Tax Dispute Resolution Committee (TDRC). If you have already received penalties, explore our specialized FTA Penalty Reconsideration & Waiver Service.
5. The 5-Year Statute of Limitations: Why 2026 is the Final Cutoff
Under FTA Public Clarification VATP046 on the Statute of Limitations, the FTA generally cannot audit a tax period or issue assessments after 5 years from the end of the relevant tax period.
6. Step-by-Step Guide: How to Submit Form 211 on EmaraTax
- Log in to EmaraTax: Access your company portal at eservices.tax.gov.ae with 2-factor authentication.
- Navigate to Tax Management: Under the VAT or Corporate Tax tile, select Tax Returns and locate the specific tax period containing the discrepancy.
- Initiate Voluntary Disclosure: Click on the actions menu and select Submit Voluntary Disclosure (Form 211).
- Enter Corrected Figures: Input the corrected standard-rated sales, zero-rated exports, or input tax recovery amounts. The portal dynamically calculates the tax difference.
- Provide Detailed Justification Letter: Draft a formal explanatory memo outlining:
- The exact root cause of the error (e.g., software migration glitch, omitted import bill).
- How the discrepancy was discovered during internal checks.
- Corrective internal controls implemented to ensure the error does not recur.
- Attach Supporting Dossier: Upload stamped general ledger extracts, corrected tax invoices, customs import declarations, and bank remittance slips.
- Submit & Settle: Submit the application and settle any resulting tax variance and administrative fees via GIBAN or FAB e-Dirham within 20 days.
📊 Case Study: Dubai Logistics Enterprise Saves AED 84,000
A multinational logistics firm in JAFZA discovered during a routine RBO mid-year review that their legacy accounting software had erroneously reported AED 1,400,000 of local mainland trucking services as zero-rated international freight across two quarterly VAT returns, understating VAT liability by AED 70,000.
RBO Action: Within 12 business days, RBO compiled a complete reconciliation dossier, drafted an official justification letter, and submitted Form 211 before any FTA audit notification.
The Outcome: The FTA approved the disclosure with a minimal 5% penalty (AED 3,500) and AED 1,000 fixed fee. Had the error been caught during an FTA audit, mandatory penalties would have exceeded AED 88,500 (50% penalty + audit non-compliance fines). Net Client Savings: AED 84,000!
Suspect a Tax Return Error? Speak with an FTA Tax Agent Today
Do not wait for an FTA audit notice. Our licensed tax agents review your general ledgers, quantify tax differences, and prepare audit-proof Voluntary Disclosures that protect your business reputation and cash flow.