Across Dubai, Abu Dhabi, and the Northern Emirates, hundreds of millions of Dirhams in legitimate tax credits remain needlessly trapped on the Federal Tax Authority (FTA) EmaraTax portal. For commercial landlords undertaking multi-million capital improvements, engineering consultants executing zero-rated cross-border projects, and general construction contractors weathering extended 60-to-120-day billing milestones, reclaiming excess input VAT is not merely an accounting exercise—it is essential working capital that directly safeguards operational solvency.
1. Commercial Real Estate & Landlords: VAT Recovery Rules & Strategies
Real estate tax law in the UAE establishes a strict legal dividing line between commercial property and residential property. Misunderstanding this distinction is the single largest reason property investors either forfeit valid refunds or trigger severe FTA audit penalties.
A. Commercial Property Leasing & Development (5% Standard Rated)
The lease, sale, or sub-lease of commercial buildings—including corporate offices in DIFC, Downtown Dubai, and ADGM, retail showrooms, shopping complexes, industrial warehouses in Al Quoz and KIZAD, and labor accommodations—is standard-rated at 5%. Consequently, registered commercial landlords are entitled to 100% input tax recovery on all ordinary business expenses directly related to these assets:
- Design, Structural & Civil Construction: 5% VAT incurred on main contractor progress billings, structural engineering, and piling contracts.
- MEP & Tenant Fit-Out Works: Mechanical, electrical, and plumbing infrastructure, HVAC installations, interior partitioning, and architectural fit-outs.
- Facility Management & Security: Routine maintenance, chiller plant services, janitorial contracts, security personnel, and landscaping.
- Professional Brokerage & Legal: Real estate broker leasing commissions, legal representation, and property management fees.
B. The 3-Year Zero-Rated Construction Rule for Residential Developers
While subsequent leasing of residential property is exempt from VAT (meaning landlords cannot recover operational input tax), Article 37 of the Executive Regulations provides a critical incentive for property developers: the first supply of a newly constructed residential building within 3 years of completion is Zero-Rated (0%).
C. Capital Assets Scheme (CAS) for Properties Exceeding AED 5,000,000
Under Article 57 of the UAE VAT Executive Regulations, single real estate assets with a total expenditure of AED 5,000,000 or more fall under the mandatory Capital Assets Scheme (CAS). CAS requires landlords to monitor and adjust their initial input tax recovery over a 10-year period. If a commercial building is subsequently converted to residential exempt leasing, or if a mixed-use building’s taxable-to-exempt ratio fluctuates, annual input tax adjustments must be reported in Box 13 of your VAT Return (Form VAT201).
2. Engineering Consultants & Architects: Unlocking Trapped Export Credits
Engineering consultancies, architectural design firms, project management offices (PMOs), and quantity surveying practices operating from Dubai, Abu Dhabi, and Sharjah frequently find themselves in chronic net refund positions. Here is why:
A. Zero-Rated Export of Services (Article 31)
Leading UAE architectural and engineering firms routinely service international property developers and infrastructure projects across Saudi Arabia (KSA), Qatar, Oman, and Europe. Under Article 31 of the Executive Regulations, services supplied to a recipient who is a non-resident and outside the State at the time the services are performed qualify as 0% Zero-Rated Exports.
Because output supplies are billed at 0%, while high-value local overheads (Grade-A office rent, advanced BIM and AutoCAD software licensing, local server infrastructure, and specialized soil/structural testing) incur 5% VAT, engineering firms accumulate substantial continuous VAT credits that should be liquidated through routine EmaraTax refund filings.
B. Reverse Charge Mechanism (RCM) for Foreign Sub-Consultants
When a UAE engineering practice engages specialized foreign facade engineers, geotechnical analysts, or acoustic consultants who do not have a physical establishment or TRN in the UAE, the service must be accounted for under the Reverse Charge Mechanism (RCM). The local consultancy declares 5% output VAT in Box 3 and simultaneously claims 5% input VAT in Box 10 of Form VAT201. Ensuring perfect documentary alignment between cross-border contracts, foreign invoices, and RCM declarations is essential to prevent FTA audit disallowances.
C. Client Reimbursements vs. Non-Taxable Disbursements
Engineering consultants frequently pay municipal planning fees, Dubai Municipality approvals, Civil Defence permits, and laboratory testing charges on behalf of project owners. Under FTA Public Clarification VATP013:
- Disbursements (Out of Scope): If the official government permit invoice is issued in the client’s name and the consultant acts solely as an paying agent, re-invoicing the exact fee without markup is not subject to VAT.
- Reimbursements (Taxable at 5%): If travel, printing, or third-party reports are incurred by the consultant to deliver their service, re-billing them to the client is considered part of the overall consideration and must carry 5% VAT.
3. General Contractors & Fit-Out Subcontractors: Solving the Cash Flow Squeeze
Construction contractors operate in one of the tightest cash flow environments in the UAE economy. Upfront cash outlays for ready-mix concrete, reinforcing steel, MEP equipment, formwork rentals, and labor accommodation carry an immediate 5% VAT cash charge, whereas project owners and developers frequently delay progress certification for 60, 90, or 120 days.
A. The Retention Money Pitfall (10% Guarantee Withholding)
Almost every standard FIDIC contract in the UAE stipulates that the employer will withhold 5% to 10% Retention Money from each Interim Payment Certificate (IPC), releasing 50% upon Practical Completion and the final 50% upon expiry of the Defects Liability Period (typically 12 to 24 months later).
B. Subcontractor Invoice Compliance & 3-Way Matching
General contractors rely heavily on trade subcontractors (plastering, glazing, HVAC, painting). During an FTA refund audit, tax inspectors rigorously scrutinize subcontractor invoices. If a subcontractor has an expired trade licence, an unverified TRN, or issues an invoice lacking mandatory Article 59 criteria, the FTA will disallow the input tax claim and issue a 20% to 50% tax assessment penalty. Engaging our dedicated accounts payable verification and TRN validation services eliminates this risk completely.
4. The 5-Step EmaraTax VAT Refund Process (Form VAT311)
Securing an approved cash disbursement into your UAE corporate bank account requires following a strict 5-stage regulatory workflow. Below is the end-to-end roadmap executed by our licensed FTA Tax Agents:
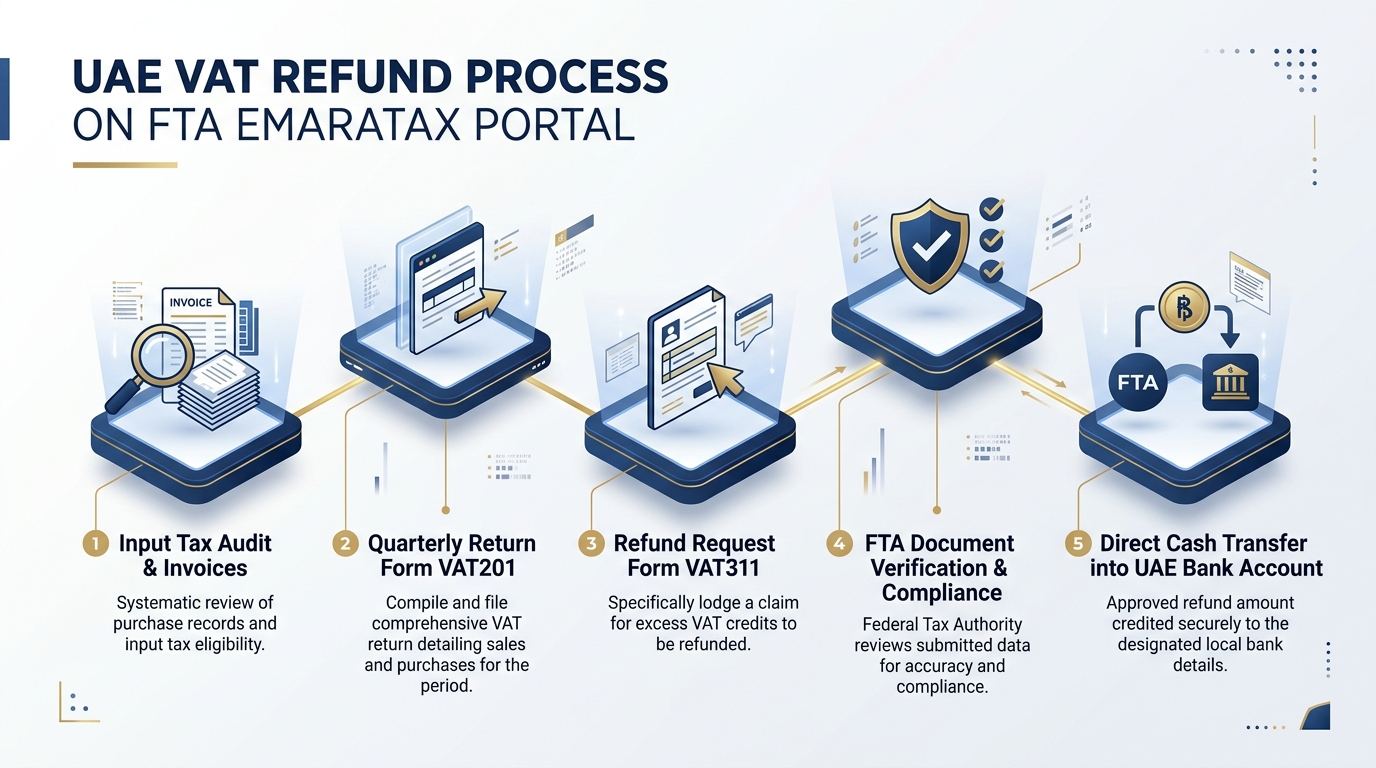
Figure 1: Official 5-Step UAE VAT Refund Roadmap from Input Tax Audit to Bank Settlement (Form VAT311).
| Stage | Action Required | Key Verification Deliverable |
|---|---|---|
| 1. Input Tax Audit | Complete pre-filing audit of all vendor tax invoices, credit notes, and payment vouchers. | Article 59 Invoice Compliance Checklist & TRN Portal Validation. |
| 2. Form VAT201 Filing | Submit quarterly VAT return establishing net excess recoverable tax in Box 14. | EmaraTax Form VAT201 Acknowledgement Receipt. |
| 3. Form VAT311 Submission | Lodge formal cash refund application on EmaraTax electing bank transfer disbursement. | Application Reference Number & Stamped Bank IBAN Letter. |
| 4. FTA Pre-Refund Audit | Respond to FTA Request for Information (RFI) questionnaire within 20 business days. | Full Audit Dossier: Top 20 Invoices, Bank Statements, BOQ & IPCs. |
| 5. Direct Cash Payout | FTA approval and automated electronic funds transfer into client corporate account. | Official FTA Refund Approval Notice & Bank Credit Advice. |
5. Sector Comparison: Landlords vs. Consultants vs. Contractors
| Industry Sector | Primary Output VAT Rate | Top Recoverable Input Expenses | Biggest VAT Risk Factor | EmaraTax Refund Strategy |
|---|---|---|---|---|
| Commercial Landlords | 5% (Standard Commercial Leases) | Construction progress billings, HVAC/MEP, building maintenance, broker fees. | Capital Assets Scheme (10-yr adjustment) & mixed-use apportionment. | Claim cash refunds during development & vacancy phases. |
| Engineering Consultants | 0% (Foreign Projects) / 5% (Local) | BIM/CAD software licenses, Grade-A office leases, specialist lab testing. | Misclassifying disbursements vs reimbursements; foreign RCM gaps. | Routine quarterly Form VAT311 filings to monetize zero-rated export credits. |
| General Contractors | 5% (Construction Milestone Billings) | Ready-mix concrete, structural steel, heavy machinery rentals, trade subcontractors. | Premature VAT on retention money; non-compliant subcontractor invoices. | Align input tax recovery directly with certified Interim Payment Certificates. |
6. Mandatory FTA Pre-Refund Audit Checklist
When you submit Form VAT311 for a refund exceeding AED 50,000, the FTA routinely issues an automated pre-refund audit notification requiring electronic submission of verification records within 20 business days. Missing this window causes immediate rejection and forfeits the claim. Our tax team prepares this complete dossier in advance:
- Top 20 Purchase Tax Invoices: Must display the word “Tax Invoice” prominently, supplier legal name, address, supplier TRN, recipient legal name, recipient TRN, sequential invoice number, date of issue, description of supply, unit price, quantity, 5% VAT rate, VAT amount in AED, and gross total in AED (Article 59).
- Unbroken Proof of Payment Trail: Stamped corporate bank statements, telegraphic transfer (SWIFT) advices, or clearing vouchers proving that every claimed invoice has been settled in full.
- Commercial Contracts & Subcontracts: Fully executed contracts, FIDIC agreements, client purchase orders, and Letters of Award.
- Interim Payment Certificates (IPCs): Engineer-certified IPCs and progress measurement sheets supporting every progress billing.
- Reconciliation Trial Balance & General Ledger: Extracted directly from cloud accounting software like Zoho Books, QuickBooks, or Xero, reconciled with the company’s Corporate Tax Returns (Form CT201).
7. What to Do If the FTA Rejects Your VAT Refund Claim
If the FTA partially disallows your input tax or rejects your Form VAT311 refund application due to alleged documentation discrepancies, do not panic. Under Federal Decree-Law No. 28 of 2022 on Tax Procedures, you have the statutory right to challenge the decision:
- Request for Reconsideration: Submit a formal appeal through EmaraTax within 40 business days of the decision, presenting supplemental proof of payment, corrected tax invoices, or legal clarifications under Cabinet Decision No. 105. Learn more in our guide to FTA penalty reconsiderations and waivers.
- Tax Disputes Resolution Committee (TDRC): If reconsideration is rejected, escalate the matter before the Ministry of Justice TDRC.
Need an FTA Tax Agent to Unlock Your Trapped VAT Refund?
RBO Accounting Services FZE represents commercial landlords, top-tier engineering consultancies, and construction contractors across Dubai, Abu Dhabi, and Ajman. We conduct thorough pre-refund health checks, prepare flawless audit dossiers, file Form VAT311, and liaise directly with FTA auditors until cash is deposited in your bank account.