With the initial filing deadlines for Federal Decree-Law No. 47 of 2022 on Corporate Tax now closed and quarterly VAT reporting entering its eighth mature year, the UAE Federal Tax Authority (FTA) has officially escalated from registration enforcement into an aggressive era of risk-based post-filing tax audits. Under Federal Decree-Law No. 28 of 2022 on Tax Procedures, tax inspectors are actively auditing general ledgers, scrutinizing intercompany transfer pricing arrangements, verifying vendor tax invoices line by line, and assessing severe administrative penalties against non-compliant entities. Navigating an official FTA Tax Audit requires disciplined technical preparation, meticulous statutory reconciliation, and licensed FTA Tax Audit Assistance.
An FTA Tax Audit is an official examination conducted by Federal Tax Authority officers to inspect a taxable person’s commercial books, general ledgers, VAT returns, Corporate Tax Form CT201 computations, customs records, and bank statements. Under Article 46 of the UAE Tax Procedures Law, the FTA holds a standard 5-year statute of limitations from the end of the relevant tax period to initiate an audit. However, in cases of suspected tax evasion or failure to register, this inspection window extends up to 15 years.
1. The 6 Major FTA Tax Audit Triggers & Red Flags in the UAE
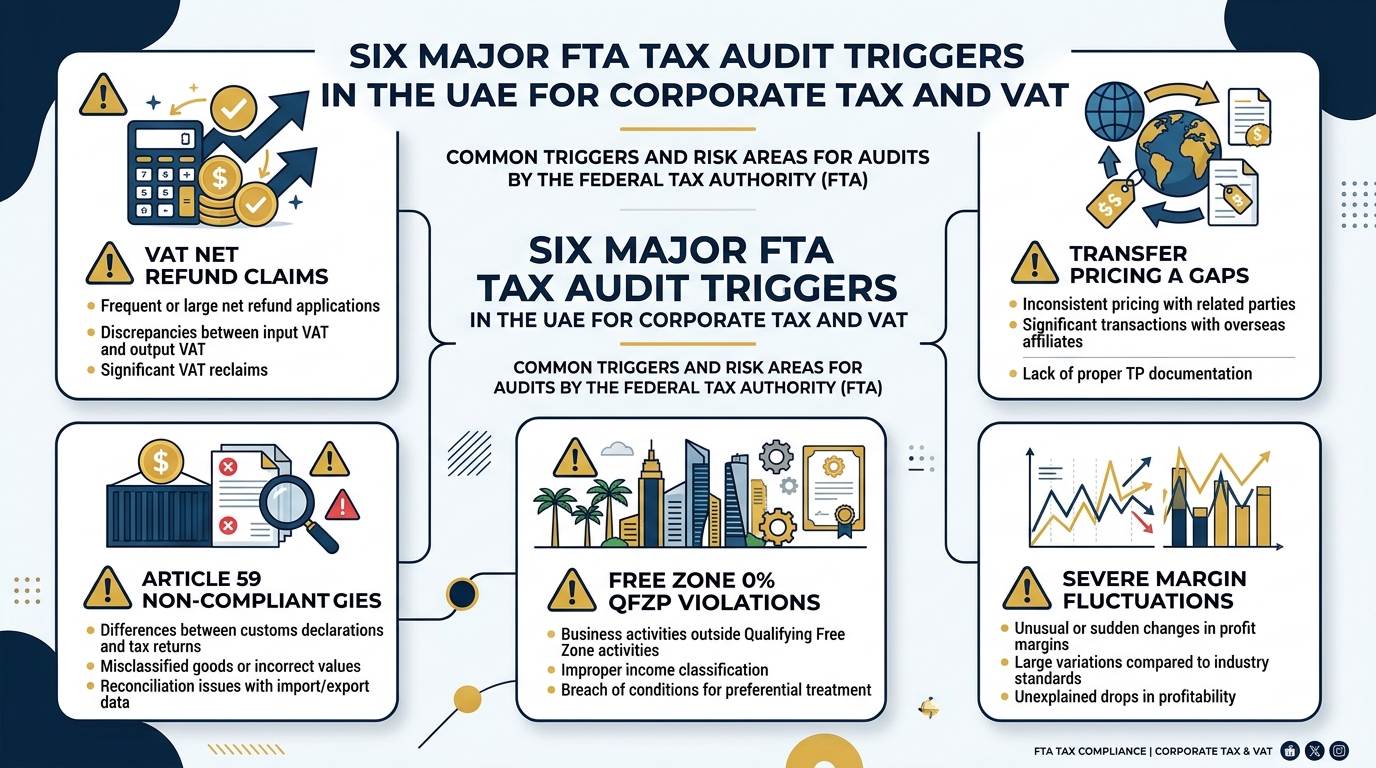
Contrary to widespread assumption, FTA tax audits are rarely random events. The Federal Tax Authority utilizes advanced risk-scoring algorithms within the EmaraTax digital portal that cross-reference submitted Corporate Tax returns, quarterly VAT201 declarations, customs import declarations, and bank reporting data. The following six operational anomalies represent the primary audit triggers:
1
Persistent VAT Net Refund Positions (Box 14 Reclaims)
While businesses operating in zero-rated export sectors (engineering consultants, commercial landlords, international logistics) legitimately accumulate excess input tax, businesses in standard commercial sectors reporting consecutive quarters of net VAT refunds automatically trigger automated system audits. Before releasing funds under Form VAT311, the FTA deploys an audit officer to inspect every underlying purchase voucher. If you are preparing a refund claim, our UAE VAT Refund Claim Guide outlines essential documentation protocols.
2
Related-Party Transactions Lacking Transfer Pricing Documentation
Under Article 34 of the Corporate Tax Law, all transactions between related parties and connected persons must adhere strictly to the Arm’s Length Principle. Disproportionate management fees, interest-free intercompany shareholder loans, or intellectual property royalties between Dubai mainland parent companies and offshore subsidiaries without a formal Local File and Master File benchmark study invite immediate tax adjustments and transfer pricing reassessments.
3
Discrepancies Between Customs Declarations & VAT Return Box 6/7
The FTA maintains seamless digital integration with Dubai Customs, Abu Dhabi Customs, and Federal Customs Authority portals. If the CIF value of imported goods registered against your Trade Licence/Customs Code does not match the auto-populated or declared figures in Box 6 (Imports subject to VAT) or Box 7 (Adjustments to goods imported into the UAE), an automated variance flag is raised for an audit review.
4
Non-Compliant Supplier Invoices & Invalid Tax Records (Article 59 Violations)
Under Article 59 of Cabinet Decision No. 52 of 2017, input VAT can only be recovered if the taxable person possesses a valid tax invoice stating the words “Tax Invoice”, the supplier’s verified TRN, a unique sequential invoice number, and explicit VAT breakdowns. Companies that lack rigorous accounts payable 3-way matching and TRN validation face total input tax disallowance plus a 20% to 50% penalty during an FTA audit.
5
Claiming 0% Free Zone Corporate Tax Without Qualifying Substance
Free Zone companies electing for 0% Qualifying Free Zone Person (QFZP) status under Ministerial Decision No. 265 of 2023 are subjected to targeted post-filing audits. If non-qualifying revenue exceeds the 5% de minimis cap (or AED 5,000,000), or if the company cannot prove adequate physical office space and full-time technical staff inside the free zone, the FTA retroactively revokes 0% status, imposing 9% tax across all revenues for 5 consecutive years.
6
Significant Margin Fluctuations vs. UAE Industry Benchmarks
If a trading company historically reports a 16% gross profit margin, and suddenly drops to 2% in the financial year UAE Corporate Tax becomes effective, tax intelligence engines detect artificial profit depression. Unless backed by verifiable market price drops, currency swings, or inventory obsolescence write-downs audited under IFRS, auditors will reconstruct revenue and recompute tax liability.
2. The 5-Stage Official UAE FTA Tax Audit Process & Response Timeline
When the Federal Tax Authority decides to conduct an audit, the process adheres to strict statutory protocols outlined in the UAE Tax Procedures Law. Below is the end-to-end audit roadmap:
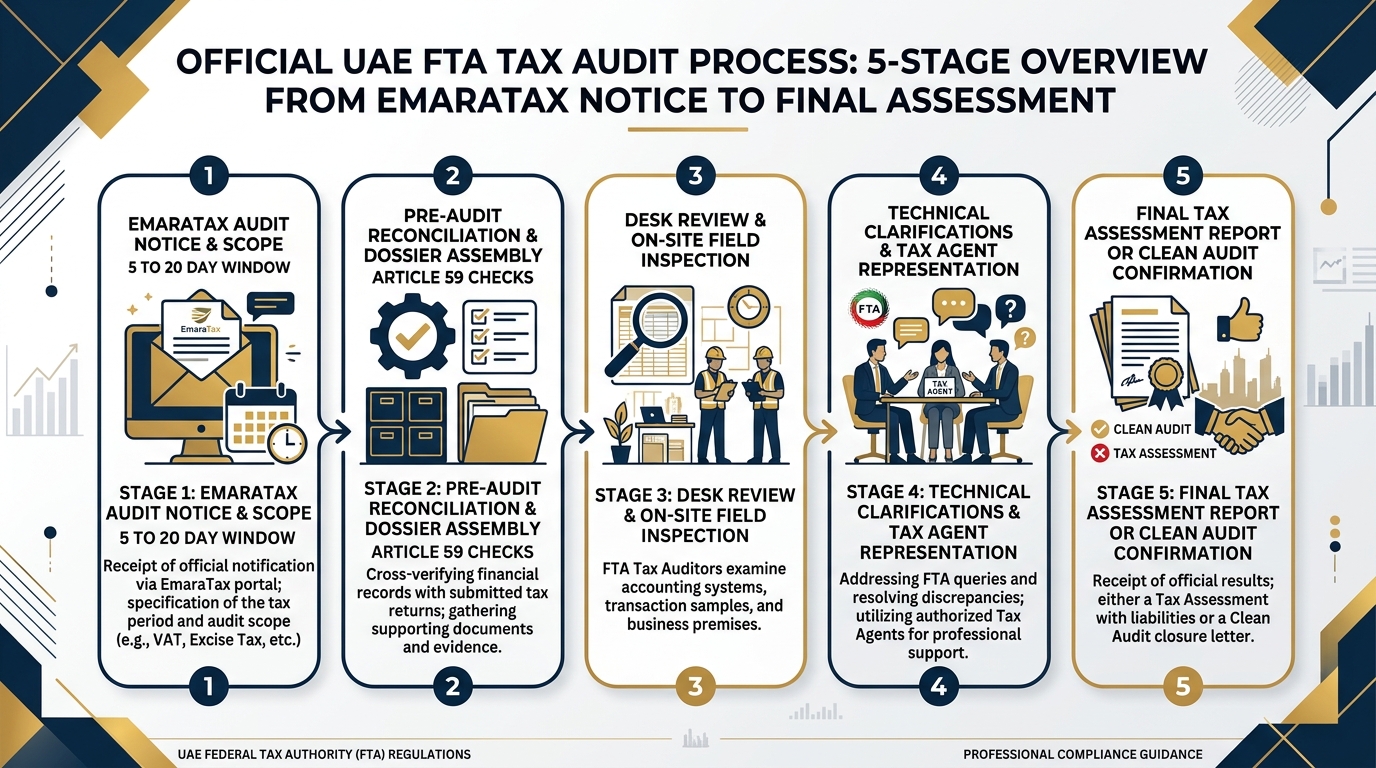
EmaraTax Notice & Scope
The FTA issues an official Audit Notification via EmaraTax specifying the tax periods, taxes under review (VAT, Corporate Tax, Excise), audit start date, and deadline (typically 5 to 20 business days).
Pre-Audit Dossier Assembly
Our licensed Tax Agents reconcile general ledgers against tax returns, inspect sample invoices, verify export customs bills, and compile Arabic/English audit schedules.
Desk Review / Field Inspection
FTA auditors conduct either an electronic desk review of submitted files or visit company premises/warehouses to inspect stock, POS registers, and physical books.
Clarifications & Representation
Tax inspectors issue queries regarding specific entries. RBO’s registered Tax Agents submit formal technical responses, legal memoranda, and supplementary reconciliation exhibits.
Assessment or Clean Closure
The FTA issues an official Audit Results Notification: either a Clean Audit confirmation or a Tax Assessment with liabilities. If penalties are contested, we initiate an immediate FTA Penalty Reconsideration.
3. The Essential Pre-Audit Documentation Checklist (The 8 Mandatory Records)
Under Article 78 of Federal Decree-Law No. 8 of 2017 and Article 56 of Federal Decree-Law No. 47 of 2022, every taxable person in the UAE must retain and be ready to present the following eight core records during an audit:
| Mandatory Record | Specific Documentation Required by FTA Auditors | Statutory Legal Reference |
|---|---|---|
| 1. Audited Financial Statements | Signed, stamped annual financial statements prepared under IFRS by an accredited UAE auditor. Required for Free Zone CT 0% and businesses over AED 50M revenue. | Article 54, CT Law No. 47/2022 |
| 2. General Ledger & Trial Balance | Electronic accounting database extracts (Zoho Books, QuickBooks, Xero, SAP) showing transaction-level dates, descriptions, accounts, and VAT/CT postings. | Article 78, VAT Law No. 8/2017 |
| 3. Sales Tax Invoices & Credit Notes | Sequential sales invoices stating customer TRN, clear taxable supply descriptions, 5% or 0% tax classifications, and corresponding credit notes. | Article 59, VAT Executive Regs |
| 4. Supplier Tax Invoices & PO Matching | Valid vendor invoices featuring the supplier’s verified TRN, company name, purchase orders (POs), and goods received notes (GRNs) for all input VAT claims. | Article 54 & 59, VAT Law |
| 5. Customs Import & Export Proofs | Official Customs Bills of Entry (import declarations), airway bills, bills of lading, and exit certificates substantiating zero-rated export sales under Article 30. | Article 30, VAT Executive Regs |
| 6. Bank Statements & Reconciliations | Monthly corporate bank statements for all active AED and foreign currency accounts with line-by-line bank reconciliation reports matching ledger cash balances. | Tax Procedures Law No. 28/2022 |
| 7. Fixed Asset Register & Depreciation | Itemized asset schedules detailing acquisition cost, purchase invoices, physical location, useful life, depreciation method, and tax depreciation adjustments. | Article 28, Corporate Tax Law |
| 8. Transfer Pricing Local/Master Files | Intercompany commercial contracts, functional analysis, comparable bench studies, and transfer pricing documentation substantiating arm’s length pricing. | Article 55, Corporate Tax Law |
4. Desk Audit vs. On-Site Field Audit: Key Differences
Depending on the severity of the flagged anomalies, the FTA will conduct either an electronic desk review or an unannounced on-site visit. Understanding the operational distinction is critical:
| Feature | Electronic Desk Audit (Remote) | On-Site Field Tax Audit (Premises Visit) |
|---|---|---|
| Location of Audit | Conducted remotely via EmaraTax portal & secure file uploads. | Conducted at your corporate offices, retail stores, or warehouses. |
| Notice Period | Typically 5 to 20 business days advance notification. | Minimum 5 business days advance notice (zero notice for suspected fraud). |
| Scope of Inspection | Sample general ledger accounts, high-value invoices, and specific VAT boxes. | Physical stock counts, cash registers, server logs, hardcopy contracts, and staff interviews. |
| Inspector Presence | Communication via official email, EmaraTax messaging, and video conferences. | FTA Tax Auditors present on-site with legal authorization and badges. |
5. Penalties for Audit Non-Compliance & Inaccurate Submissions
Under Cabinet Decision No. 40 of 2021 and Cabinet Decision No. 75 of 2023, non-compliance during an audit or submitting inaccurate records carries severe statutory consequences:
- Failure to Keep Financial Records: AED 10,000 for the first offense; AED 20,000 for repeat offenses.
- Failure to Submit Documents Within the Specified Window: AED 20,000 fine for failing to provide records requested by the FTA auditor.
- Submitting an Inaccurate Tax Return (Disallowed Deductions): Fixed penalty of AED 1,000 (first time) or AED 2,000 (repeat) PLUS a percentage penalty ranging between 20% to 50% of the unpaid tax amount.
- Late Payment of Assessed Tax: Monthly compounding late payment interest of 1% per month on the outstanding tax liability until settled.
- Failure to Facilitate the Work of the Tax Auditor: AED 20,000 fine for obstructing inspectors or failing to grant access to physical records or warehouses.
6. Pre-Audit Health Check: How RBO’s Mock Audits Eliminate Tax Risk
The single most effective defense against devastating tax fines is conducting a Pre-Audit Tax Health Check. In this diagnostic exercise, RBO’s licensed FTA Tax Agents act as independent tax inspectors, subjecting your financial books to the exact forensic scrutiny used by the Federal Tax Authority:
- VAT & Corporate Tax Cross-Reconciliation: We match revenue reported in your VAT returns with revenues declared on Corporate Tax Form CT201, resolving timing differences and revenue recognition mismatches.
- Article 59 Invoice Integrity Audit: We audit your accounts payable vendor database, verifying TRNs on the FTA portal and identifying missing tax invoices or non-compliant vouchers before the FTA disallows your input tax.
- Transfer Pricing & Related-Party Review: We examine intercompany transactions, management charges, and loan agreements, ensuring arm’s length benchmarking documentation is airtight.
- Zero-Rated Export File Audit: We inspect export documentation for Article 30 compliance, ensuring customs exit certificates and commercial shipping bills match zero-rated declarations in Box 5 of Form VAT201.
- Pre-Emptive Voluntary Disclosure Submission: If material errors exceeding AED 10,000 are identified, our Tax Agents draft and submit Form 211 on EmaraTax, locking in the lowest penalty bracket before an audit notice is triggered.
7. Real-World Case Study: Dubai Distribution Enterprise Survives Comprehensive FTA Audit
📊 Case Profile: JAFZA Logistics & Wholesale Firm (AED 42,000,000 Turnover)
A multinational trading business operating in Jebel Ali Free Zone received an official EmaraTax Audit Notification for 8 consecutive quarters of VAT returns and their initial Corporate Tax filing. The company had claimed significant input tax on foreign freight forwarding services and substantial bad debt relief, attracting intense FTA scrutiny with only a 15-day submission deadline.
The RBO Tax Audit Defense Execution:
- Mobilized an emergency on-site audit team within 24 hours to review general ledger transaction lines totaling over AED 85M.
- Re-verified 320 high-value supplier invoices against Article 59 criteria, obtaining amended tax invoices from overseas carriers.
- Prepared a formal legal memorandum under Article 64 of the VAT Law substantiating the bad debt relief claim with documented bankruptcy filings and court notices.
- Acted as the official appointed Tax Agent on EmaraTax, managing all communications and attending technical interrogation sessions with FTA tax inspectors.
Net Outcome: The FTA issued an official Clean Audit Closure Letter with Zero Tax Assessments and Zero Penalties, successfully protecting over AED 640,000 in contested input tax deductions.
Received an FTA Audit Notice or Need a Pre-Audit Health Check?
Do not face tax inspectors alone. Partner with RBO Accounting’s licensed FTA Tax Agents and former tax auditors for end-to-end representation, dossier compilation, and audit defense in Dubai, Abu Dhabi, and Northern Emirates.
8. Frequently Asked Questions: FTA Tax Audits in UAE
How much advance notice does the FTA give before starting a tax audit?
Under the UAE Tax Procedures Law, the FTA typically provides at least 5 business days advance notification before conducting a tax audit. For complex desk audits, the notice period and document submission window is often extended to 10 to 20 business days. In rare cases where tax evasion is suspected, the FTA may conduct an unannounced field inspection without prior notice.
Can a company appoint an external Tax Agent to represent them during an FTA audit?
Yes. Under UAE Tax Law, taxable persons have the full legal right to appoint a licensed, FTA-registered Tax Agent or approved tax agency to represent them. The Tax Agent communicates with the tax inspectors, prepares formal submissions, attends meetings, and submits legal rebuttals on your behalf via the EmaraTax portal.
What happens if our company cannot find supporting tax invoices for input VAT claimed?
If an invoice cannot be produced or does not satisfy Article 59 criteria (e.g., missing supplier TRN, issued to wrong entity name), the FTA auditor will disallow the input tax deduction. The disallowed amount must be repaid with an additional 20% to 50% percentage penalty plus 1% monthly compounding late payment interest.
How long must businesses in UAE retain accounting and tax records?
Under UAE Federal Tax Procedures Law and Corporate Tax Law, businesses must retain accounting books, commercial records, tax invoices, and bank statements for a minimum of 7 years following the end of the financial year. For real estate assets under the Capital Assets Scheme, records must be retained for at least 15 years.
Can we request an extension if we cannot submit audit documents in time?
Yes. A taxable person or their appointed Tax Agent can submit a formal request for an extension via EmaraTax before the initial deadline expires, providing legitimate justification (e.g., historical archival retrieval, complex multi-entity consolidation). However, granting the extension remains strictly at the FTA’s discretion.
What is the difference between an FTA Tax Assessment and an Administrative Penalty?
A Tax Assessment is an official recalculation by the FTA of the principal tax liability you owe due to incorrect calculations or disallowed deductions. An Administrative Penalty is a fine imposed for breaching procedural obligations (such as late filing, failing to keep records, or submitting inaccurate declarations).
Can we appeal an adverse FTA Tax Audit Assessment?
Yes. Taxable persons have the legal right to submit a formal Request for Reconsideration within 40 business days of receiving the assessment. If rejected or partially accepted, the dispute can be escalated to the Tax Disputes Resolution Committee (TDRC) and subsequently to the Federal Courts.
How does RBO Accounting support businesses during an FTA tax audit?
RBO provides turnkey audit defense: we perform pre-audit forensic reviews, assemble complete statutory dossiers, identify legal defenses for contested transactions, represent your firm on EmaraTax, interface directly with FTA auditors, and submit formal responses to resolve queries with minimal or zero financial liabilities.